Most trucking business owners assume their commercial truck policy will cover lost income if a fire, severe storm, or accident forces them to shut down. That assumption can be dangerously costly. Business interruption insurance (BI) is a separate and specific coverage that protects your revenue and ongoing expenses when a covered event stops your operation, and understanding exactly how it works is one of the most important risk management decisions you can make as a fleet owner or manager. This article breaks down what BI insurance covers, how claims are triggered, and what practical steps you can take to protect your company’s financial stability.
Table of Contents
- What is business interruption insurance?
- What does business interruption insurance cover?
- How business interruption insurance works: Triggers, exclusions, and restoration period
- Business interruption insurance for trucking and logistics: Industry-specific extensions
- Best practices for filing a business interruption claim
- What most trucking companies overlook about business interruption insurance
- Cost factors and saving tips for refrigerated trucking insurance
- Protect your trucking business with the right insurance partner
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Covers lost income | Business interruption insurance pays for lost revenue and key expenses if your trucking business is disrupted by a covered event. |
| Requires physical damage | Most policies only cover losses from physical damage at your location or a connected supplier or customer site. |
| Includes industry extensions | Trucking businesses can add coverage for road closures, utility outages, and dependent properties by choosing BI policy extensions. |
| Document claims thoroughly | Keeping detailed financial records is essential for maximizing your BI insurance claim. |
| Policy wording matters | Work with a trucking insurance specialist to align your coverage with your actual business risks and operations. |
What is business interruption insurance?
Business interruption insurance is a form of coverage designed to replace income your business loses when operations are suspended because of a covered physical loss. For trucking companies, that means BI steps in to help pay your bills when a fire destroys your terminal, a tornado damages your warehouse, or a major equipment loss forces you to suspend dispatch. It does not replace the damaged property itself. That is what your commercial property coverage handles. BI fills the financial gap between when the damage happens and when you are back to normal operations.
As truckers’ insurance specialists consistently emphasize, the mechanics of BI are more precise than most operators expect. Coverage is generally triggered by a policy-defined event and is commonly tied to a “period of restoration,” which can include a waiting period before payments begin. That waiting period is often 48 to 72 hours, meaning you absorb the first day or two of loss before the policy pays out.
BI insurance commonly pays for lost revenue and certain continuing fixed costs, and may be paired with “extra expense” or mitigation costs. For a trucking company, fixed costs include ongoing loan payments on equipment, employee payroll for drivers and office staff, property rent or lease payments, and insurance premiums that continue whether your trucks are rolling or sitting idle. Extra expense coverage is equally valuable because it allows you to spend money to speed up your recovery, such as renting substitute equipment, leasing a temporary office, or paying expedited shipping fees to serve clients through a third party.
Understanding your insurance needs for trucking companies starts with recognizing that BI is not typically a standalone product. It is added to or bundled with a commercial property policy, and its limits and terms are directly shaped by your policy language.
What does business interruption insurance cover?
The core of any BI policy is the replacement of lost business income, meaning the net profit your business would have earned plus the fixed expenses you still owe, even with your trucks parked.
BI insurance commonly pays for lost revenue and continuing fixed costs, and may be paired with extra expense coverage that helps you pay for costs incurred to shorten the shutdown and resume operations faster. But spoiled cargo itself is a different animal. That loss is generally handled by motor truck cargo insurance, not by the BI portion of your policy. The table below separates the two so you can see which coverage actually responds to each scenario.
| Coverage category | What it includes | Refrigerated trucking example |
|---|---|---|
| Lost business income (BI) | Net profits lost while your operation is shut down by a covered physical loss | Terminal fire halts dispatch for six weeks; BI pays the lost freight income |
| Fixed operating expenses (BI) | Rent, payroll, loan payments, taxes owed during the shutdown | Terminal lease, driver salaries, reefer trailer financing |
| Extra expenses (BI) | Costs to accelerate recovery and shorten the shutdown period | Temporary dispatch office, expedited repairs |
| Motor truck cargo with spoilage coverage | Compensation for perishable goods lost to refrigeration unit failure, temperature deviation, or power outage | A reefer unit fails mid-route and a full trailer of seafood spoils |
| Reefer breakdown insurance | Losses from mechanical defects, power supply interruptions, or sensor and thermostat failures in the refrigeration unit | The thermostat malfunctions and the unit runs warm for eight hours without triggering an alarm |
| Cargo contamination coverage | Losses when perishable goods are contaminated by exposure to harmful substances or bacteria during transit | A leaking chemical shipment on the same trailer taints an adjacent pallet of produce |
BI responds to income lost because your business operation is interrupted by physical damage to your property, not to the value of the freight sitting in the trailer. If your terminal burns down and you cannot dispatch trucks, BI pays your lost income and fixed costs. If a reefer unit fails on the highway and the load spoils, that is a cargo loss, and it needs to be covered under motor truck cargo insurance with spoilage coverage, or under reefer breakdown insurance if the cause is a mechanical, power, or sensor failure in the unit itself.
Triggers for this kind of claim typically involve a power outage that knocks out the refrigeration system or an equipment failure in the unit itself. Basic cargo insurance may not respond to temperature-related spoilage at all, which is why reefer breakdown coverage needs to be added specifically for refrigeration equipment malfunctions rather than assumed as part of a standard cargo policy.
Imagine your trucking terminal suffers a serious fire. Roof damage and smoke contamination force you to close the facility for six weeks while repairs are completed. During that time, you still owe rent on the property, payroll to your administrative staff, and monthly loan payments on your fleet. BI coverage would pay those continuing fixed costs, along with the net profit you would have earned from freight runs. If you also choose to rent a temporary dispatch space to keep partial operations going, your extra expense coverage handles that cost as well.
Now contrast that with a reefer scenario. Your refrigerated trailer is en route with a load of dairy products when the unit’s compressor fails overnight. By the time the driver notices the alarm, the cargo has warmed past safe temperature for hours and the load is a total loss. This event does not shut down your terminal or interrupt your business operations, so BI does not apply. Instead, the claim runs through your motor truck cargo policy’s spoilage provision, or through reefer breakdown insurance if the mechanical failure of the unit is the documented cause.
Choosing the best insurance for your trucking operation involves more than comparing premiums. It means knowing which policy pays for which loss. Some cargo policies exclude spoilage caused by improper pre-trip maintenance or driver error in setting temperature controls, so reviewing the fine print with a specialist before you file a claim is essential.
Review how your policy is structured against your insurance requirements for trucking companies to confirm two things: that your BI limits cover your actual monthly fixed costs, and separately, that your cargo policy explicitly names spoilage and refrigeration breakdown as covered causes of loss rather than leaving them implied.
Pro Tip: Before any loss occurs, prepare a spreadsheet listing every fixed expense your operation carries each month, and a second list of your highest-value perishable cargo categories. Include loan payments, lease obligations, payroll by category, and the declared value of goods like seafood, dairy, or pharmaceuticals. Having both documents ready at claim time speeds up the adjustment process, whether the claim runs through BI or through your cargo policy.
How business interruption insurance works: Triggers, exclusions, and restoration period
Understanding what BI insurance covers leads to a deeper question: when does it actually apply, and when doesn’t it? This is where many trucking business owners run into problems, because the trigger for a BI claim is more specific than most people assume.
Most BI policies require direct physical loss or damage to property. Many BI policies require direct physical loss or damage at the insured premises, or at relevant “dependent property” locations for contingent BI, so some shutdowns without covered physical damage are often excluded. This matters enormously for trucking companies facing disruptions that do not involve obvious property damage, such as a regulatory shutdown, a labor dispute, or a drop in freight demand.
Here is how the claim process typically unfolds for a covered loss:
- A covered peril, such as fire, windstorm, or vandalism, causes physical damage to your insured premises or dependent property.
- The damage forces a full or partial suspension of your business operations.
- Your waiting period begins. This is commonly 48 to 72 hours after the triggering event.
- Once the waiting period passes, BI payments begin to accrue daily.
- Coverage continues through the restoration period, which ends when repairs are complete or when your business could reasonably resume operations, whichever comes first.
- Extra expense reimbursements are submitted alongside your ongoing loss documentation.
Common exclusions you need to know include economic losses from market downturns or contract cancellations, losses from events that do not cause physical damage, losses from events specifically excluded by your policy such as floods without a flood endorsement, and losses caused by government-mandated closures that are not tied to physical damage. The COVID-19 pandemic exposed this exclusion for countless businesses across all industries.
Cyber risk is another emerging concern for transportation companies. Cyber policies may offer BI-like coverage, but standard property-based BI policies often do not cover income losses from a cyberattack unless a cyber endorsement is specifically added. If your dispatch system or fleet management software is compromised and shuts down your operation, you may find your standard BI policy offers no protection without that endorsement.
Working with trucking insurance experts to review your policy language is not optional. It is a fundamental part of protecting your business. When you compare insurance providers for trucking companies, make sure you ask specifically about cyber endorsements and whether your policy requires physical damage as a trigger.
Pro Tip: Read the definition of “covered cause of loss” in your BI policy carefully. If that section does not explicitly include cyber events, utility failures, or government orders, your coverage for those scenarios is likely absent or severely limited.
Business interruption insurance for trucking and logistics: Industry-specific extensions
Having reviewed general triggers, let us highlight coverages designed specifically for the complexities of trucking and logistics, and for refrigerated operations in particular. The transportation sector faces disruption risks that standard BI policies may not address without targeted extensions, and refrigerated carriers face an added layer that generic trucking policies were never built to handle: temperature-sensitive cargo.
In trucking and transportation risk management, BI concepts matter when operations or access are disrupted, but buyers need to understand how physical-damage triggers and endorsements apply. Here is a breakdown of the extensions relevant to a general trucking operation.
Contingent business interruption. This extension covers income losses when a key supplier, customer, or dependent property suffers a covered physical loss. For a trucking company, this could mean a major shipper’s warehouse burns down and you lose a contract worth thousands of dollars per week.
Civil authority coverage. If a government agency, such as a fire marshal or emergency management office, restricts access to your facility because of a covered event at a nearby property, civil authority coverage pays your lost income during that restriction period. This is particularly relevant for trucking terminals located near industrial zones.
Ingress and egress coverage. Your terminal may be undamaged, but if road damage or debris blocks the only access routes, your operation still grinds to a halt. Ingress and egress coverage protects against exactly that scenario.
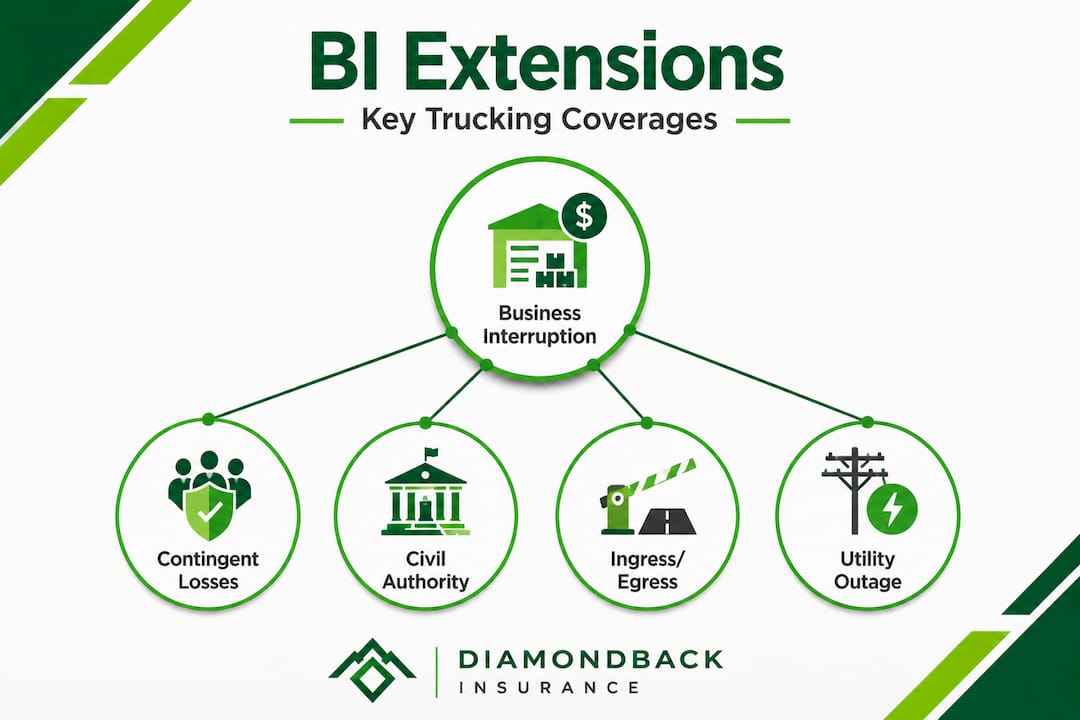
Utility service interruption. Power outages, water main breaks, or loss of natural gas can disable refrigerated storage or disrupt your facility. A utility service interruption extension can cover losses caused by those events, even when the outage originates off your property. For a refrigerated carrier, this matters at the terminal or warehouse level, but it does not extend to a reefer trailer’s compressor failing on the highway.
That gap is exactly why refrigerated trucking operations need coverage beyond classic BI. None of the extensions above pay for spoiled freight, so a comprehensive program for reefer operations layers in the following:
Reefer breakdown insurance. This covers losses from mechanical defects, power supply interruptions, and sensor or thermostat malfunctions in the refrigeration unit itself. If your trailer’s cooling system fails from a bad compressor or a miscalibrated thermostat, this is the policy that responds, not BI and not standard cargo insurance.
Motor truck cargo insurance with spoilage coverage. Basic cargo insurance may not cover temperature-related spoilage at all. Spoilage coverage has to be added specifically so that losses from refrigeration unit failures, temperature deviations, and power outages during transit are compensated.
Cargo contamination coverage. Some motor truck cargo policies include protection against financial losses when perishable goods are contaminated by exposure to harmful substances or bacteria, a distinct risk from mechanical breakdown but one that also ends in a spoiled or unsellable load.
Commercial auto liability insurance. This covers bodily injury and property damage from accidents, including incidents that occur while loading and unloading perishable goods at ports and warehouses.
Physical damage insurance. This covers repairs or replacement of the vehicle and the refrigerated unit itself when damaged by accidents, weather, or theft, separate from the value of the cargo it was carrying.
General liability insurance. This protects against claims from third-party injuries, property damage, or food safety liability if contaminated or spoiled product actually reaches a consumer.
Here is how to decide which of these belong in your program. If your fleet hauls high-value perishables like seafood, dairy, or pharmaceuticals, reefer breakdown and spoilage-endorsed cargo coverage are not optional add-ons, they are the core protection for your freight. If your routes run through industrial corridors or areas prone to road closures, civil authority and ingress and egress extensions protect your terminal-level income. Knowing which of these extensions and endorsements are attached to your current policy is part of a responsible risk management review. Protect your trucking business by auditing your existing coverage for these endorsements before a disruption forces the question.
Best practices for filing a business interruption claim
Knowing your coverage extensions is only half the battle. Here is how to maximize your benefit if you need to make a claim. The single most common reason BI claims fall short is inadequate pre-loss documentation. Insurers calculate your lost income by comparing what your business actually earned against what it would have earned without the interruption. If your financial records are incomplete, inconsistent, or hard to reconstruct, that calculation works against you.
BI claims can be disputed and hinge on claim documentation and adjustment methodology, for example, projecting revenue using financial history and selecting the baseline trend period. That means the time frame your insurer uses to project your pre-loss revenue trend can significantly affect your payout. If your business was growing fast in the months before a loss, you want that growth reflected in the projection. Disputes over this methodology are common and can be costly if you are unprepared.
Follow these steps to strengthen your claim:
- Assess the scope of the disruption immediately and note the date and time of the triggering event.
- Notify your insurer as soon as possible. Most policies require prompt notice, and delays can jeopardize coverage.
- Document all physical damage with photographs, repair estimates, and contractor invoices.
- Compile financial records including the past two to three years of tax returns, profit and loss statements, and monthly revenue reports.
- Track all extra expenses separately, keeping every receipt and vendor invoice from the moment operations are disrupted.
- Consider hiring a public adjuster or claims consultant if the loss is large or if your insurer disputes the revenue projection methodology.
“The strength of a BI claim is directly tied to the quality of the financial and operational records supporting it. Businesses that document proactively recover faster and more completely.”
Trucking insurance claims guidance from experienced professionals can make a measurable difference in the final settlement amount. Do not wait until a loss occurs to understand the claims process.
Pro Tip: Begin organizing your records at the very first sign of a potential disruption, even before the loss is fully confirmed. Early documentation protects your timeline and prevents memory gaps that adjusters may use to challenge your claim.
What most trucking companies overlook about business interruption insurance
Here is the perspective that most articles skip over. Trucking operators invest significant time comparing liability limits and physical damage deductibles, but many give BI coverage only a cursory review. The result is a dangerous coverage gap that only becomes visible at exactly the worst moment.
The most critical misunderstanding is this: BI is not simply a policy that pays whenever your trucks are not running. A recurring underwriting and claims nuance is that BI is not simply “economic loss from downtime.” Courts and insurers often require that the downtime be legally caused by a covered peril as defined in the policy wording. That distinction has denied legitimate-feeling claims for countless businesses, from small carriers to large fleets.
The lesson is straightforward but important. Policy intent and policy language are not the same thing. You might reasonably assume your BI coverage kicks in whenever a major disruption halts your operation, but if that disruption does not meet the exact definition of a covered cause of loss in your specific policy, coverage will not apply. Insurers are not being unreasonable when they deny these claims. They are enforcing the contract you agreed to.
The solution is to work with a specialist who can audit your actual operations against your policy wording, identify the gaps, and recommend specific endorsements to address them. Insuring your trucking company correctly is not a one-time transaction. It is an ongoing process of aligning your coverage to the real risks your business faces.
Cost factors and saving tips for refrigerated trucking insurance
Four factors drive what you pay for BI and related coverage on a refrigerated fleet:
- Cargo value limits. High-value perishables like seafood, dairy, and pharmaceuticals push up the coverage limits you need, so match your limits to what you actually haul rather than a generic default.
- Reefer unit reliability. Coverage for mechanical failures, power interruptions, and sensor faults under reefer breakdown insurance costs less when your units are well maintained.
- Geographic and regulatory factors. Distances traveled and compliance requirements like the Food Safety Modernization Act (FSMA) shape your risk profile and your rate.
- Claims history. Fewer past spoilage or contamination claims gives you more room to negotiate lower rates.
To manage costs, keep reefer maintenance records current, right-size cargo limits to your actual freight mix, and review your BI, reefer breakdown, and cargo endorsements together rather than shopping each in isolation.
Protect your trucking business with the right insurance partner
Business interruption insurance is one of the most misunderstood yet most financially critical coverages available to trucking companies. Getting it right requires more than a standard policy review. It means understanding triggers, exclusions, restoration periods, and the extensions that apply specifically to transportation operations.
At Diamondback Insurance, we make it simple to compare trucking insurance explained options from multiple top-rated carriers in one place. Whether you need to close a BI coverage gap, add a contingent BI extension, or review your full fleet program, our platform lets you find trucking insurance companies and compare quotes instantly. Working with the right insurance partners for truckers means your operation has a complete risk management foundation, not just basic compliance coverage.
Frequently asked questions
Does business interruption insurance require physical damage to my property?
Many BI policies require direct physical loss or damage at the insured premises, so most standard policies only pay when a covered physical event such as a fire or storm affects your property or a dependent location.
How long does business interruption insurance coverage last?
Coverage is generally triggered by a policy-defined event and tied to a period of restoration, so coverage typically starts after a short waiting period and ends when repairs are complete or your business could reasonably reopen.
Can business interruption insurance cover losses from a power outage or road closure?
Yes, if your policy includes the right endorsements. BI-related extensions such as ingress and egress coverage and utility service interruption can apply to transportation logistics operations when those specific events are included in your policy.
What are extra expenses in a BI claim for truckers?
Extra expenses are costs you incur to keep your operation running or recover faster during a covered disruption. Mitigation-related items like temporary relocation, expedited shipping, and rental equipment are common examples that BI policies with extra expense coverage will reimburse.
How can I make a stronger BI insurance claim?
Keep detailed financial records going back at least two to three years and document all losses and extra expenses from the first day of the disruption. Projected revenue baselines are built from prior financial records, and disputes can occur over methodology choices, so the stronger your documentation, the better your position.